
 By John Egan
What Is an EMV Chip?
By John Egan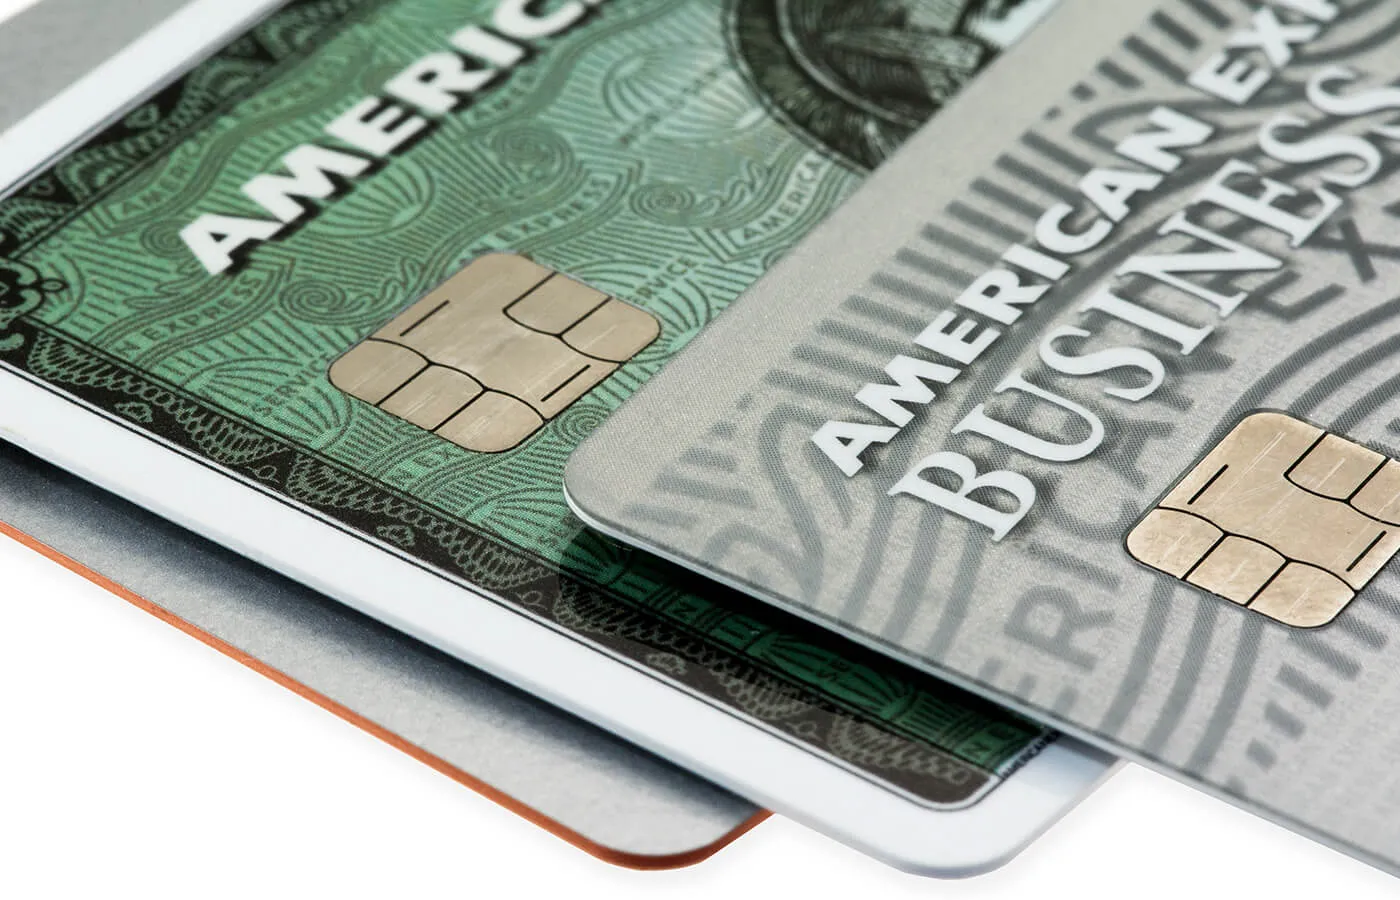
If you have a credit, debit or prepaid card, there's a good chance it has an EMV chip. EMV chips are the small, square computer chips that appear on debit, credit and prepaid cards to help safeguard them against fraud. EMV (which stands for Europay, Mastercard and Visa) chips create a one-of-a-kind code for each credit transaction.
The use of EMV chips is on the rise, with the technology showing up on close to 11 billion cards worldwide as of early 2021. Here's what you need to know about how EMV chips work and how to avoid scams that use them.
How EMV Chip Cards Work
EMV chips transmit data just as magnetic strips on cards transmit data. However, payment terminals don't read EMV chips the same way they read magnetic strips.
A card with an EMV chip typically must be inserted into the slot of a payment terminal, which then reads the chip's data and verifies the card as authentic. You then must wait for the purchase to be authorized. This process is known as "dipping."
By contrast, making a purchase by sliding a card with a magnetic strip through a card reader is called "swiping." The magnetic strip also transmits data that enables authorization of a purchase and verification of a card. A swiped transaction may be a bit quicker than a dipped transaction, but it's not quite as secure.
One key difference between an EMV card and a magnetic strip card is that the EMV card produces a unique code for each transaction but the magnetic strip does not. As such, it's harder for fraudsters to steal data to produce counterfeit cards. That's why merchants and card issuers prefer EMV transactions, even though they are more complicated than magnetic strip transactions.
Most cards in the U.S. depend on chip-and-signature capabilities. In this type of transaction, a cardholder must provide a signature to complete a transaction. Outside the U.S., chip-and-PIN transactions are more common. In these transactions, a cardholder enters a four-digit PIN to validate a payment. Chip-and-PIN transactions are considered more secure than chip-and-signature transactions.
Another way to use an EMV card is as a contactless payment method. If the card has this capability, you can tap it on a payment terminal or wave it near the terminal to complete the transaction. A contactless transaction doesn't require a PIN.
Best credit cards of 2026
Compare cards from our partners with intro bonuses, cash back or points offers, and annual fees as low as $0.
Offers from our partners
American Express Platinum Card®
Intro bonus:
As High As 175,000 points. Find Out Your Offer.
You may be eligible for as high as 175,000 Membership Rewards® Points after spending $12,000 in eligible purchases on your new Card in your first 6 months of Membership. Welcome offers vary and you may not be eligible for an offer.
Ongoing APR:See Pay Over Time APR
Rewards:
1x - 5x (Points per dollar)
Get more for your travels with 5X Membership Rewards® points on all flights and prepaid hotel bookings through American Express Travel®, including Fine Hotels + Resorts® and The Hotel Collection bookings. You earn 5X points on flights purchased directly from airlines or through American Express Travel® on up to $500,000 on these purchases per calendar year.
Annual Fee:$895
First Latitude Secured Mastercard® Cash Back Rewards
Ongoing APR:27.74% Variable
Rewards:
1% - 10% (cash back)
Earn up to 10% Cash Back on purchases at participating merchants that fit your lifestyle—from dining and grocery to retail and more—plus 1% Cash Back on payments made to your First Latitude Card.^^
Annual Fee:$0
Citi® / AAdvantage® Globe™ Mastercard®
Ongoing APR:19.74% - 29.74% (Variable)
Rewards:
1x - 6x (Miles per dollar)
Earn 6 AAdvantage® miles for every $1 spent on eligible hotels booked through aadvantagehotels.com. Earn 3 AAdvantage® miles for every $1 spent on eligible American Airlines purchases. Earn 2 AAdvantage® miles for every $1 spent at restaurants, including takeout and delivery. Earn 1 AAdvantage® miles for every $1 spent on all other purchases.
Annual Fee:$350
Credit One Bank® Wander® American Express® Metal Card
Ongoing APR:29.74% Variable
Rewards:
1% - 10% (cash back)
Earn 5% cash back rewards on eligible dining, gas, & travel purchases, 1% cash back rewards on all other purchases, and 10% cash back rewards on eligible hotel and car rentals booked using the Credit One Bank travel partner. Cash back rewards will be awarded as rewards points redeemable for a statement credit, gift cards, travel, and more. Terms apply.
Annual Fee:$95
Delta SkyMiles® Gold American Express Card
Intro bonus:
As High As 80K Miles + $250 Statement Credit
You may be eligible for as high as 80,000 Bonus Miles and a $250 Statement Credit after you spend $3,000 in eligible purchases on your new Card in your first 6 months of Card Membership. Apply to find out your offer. Terms Apply. Offer ends 11/04/2026.
Ongoing APR:19.74%-28.74% Variable
Rewards:
1x - 2x (Miles per dollar)
When you use your Delta SkyMiles® Gold American Express Card, you can earn: 2X miles on Delta Purchases, 2X miles at restaurants, 2X miles at U.S. supermarkets, 1X miles on all other eligible purchases. Every mile you earn brings you closer to the places you want to go. Turn them into your next trip, use them for seat upgrades, and more.
Annual Fee:$0 introductory annual fee for the first year, then $150.
Delta SkyMiles® Platinum American Express Card
Intro bonus:
As High As 90K Miles + $300 Statement Credit
You may be eligible for as high as 90,000 Bonus Miles and a $300 Statement Credit after you spend $4,000 in eligible purchases on your new Card in your first 6 months of Card Membership. Apply to find out your offer. Terms Apply. Offer ends 11/04/2026.
Ongoing APR:19.74%-28.74% Variable
Rewards:
1x - 3x (Miles per dollar)
Earn 3X Miles on Delta purchases and purchases made directly with hotels. Earn 2X Miles at restaurants worldwide including takeout and delivery in the U.S., and at U.S. supermarkets. Earn 1X Miles on all other eligible purchases.
Annual Fee:$350
Citi Simplicity® Card
Intro APR:0% intro APR for 18 months from account opening on purchases and qualifying balance transfers
Ongoing APR:17.74% - 28.49% (Variable)
Rewards:
N/A
Annual Fee:$0
Bank of America® Travel Rewards credit card
Intro APR:0% Intro APR for 15 billing cycles for purchases, and for any balance transfers made in the first 60 days
Ongoing APR:17.74% - 27.74% Variable
Rewards:
1.5x - 3x (Points per dollar)
3 points per $1 spent on travel purchases booked through BofA Travel and 1.5 points per $1 spent on everyday purchases
Annual Fee:$0
See all our best credit cards for 2026.
What if a Merchant Doesn't Accept EMV Cards?
EMV chip cards still come with magnetic strips, so you should be able to use an EMV card even if a merchant doesn't have the equipment required for EMV transactions.
You also may be able to use a digital wallet. Some apps store credit card information electronically, letting you pull up a digital card on a smartphone and tap the phone on a payment terminal to complete a transaction.
Watch Out for EMV Chip Scams
While EMV chip cards have helped slash payment fraud, they haven't stopped crooks from committing card-related crimes. Today, thieves are targeting EMV cards through a scam known as "card shimming."
Employing this technique, a scammer inserts a thin device called a shim into a card reader that accepts EMV cards. This device copies and stores data from your card. A scammer can't produce another chip card with this information—however, they can produce a magnetic strip card with the data stolen from the EMV card.
To avoid being victimized by an EMV chip scam, take advantage of mobile payment apps or contactless tap-and-go functions when you're making a transaction.
The Bottom Line
To head off problems that may arise when credit card information or other personal information is compromised, enroll in free credit monitoring from Experian to help you quickly detect potential fraud. If you suspect you've been the victim of an EMV chip scam, contact your card issuer right away to report it. Checking your free Experian credit report can also alert you to suspicious activity related to your credit.
Don’t apply blindly
Apply for credit cards confidently with personalized offers based on your credit profile. Get started with your FICO® Score for free.
See your offers
About the author
John Egan
John Egan is a freelance writer, editor and content marketing strategist in Austin, Texas. His work has been published by outlets such as CreditCards.com, Bankrate, Credit Karma, LendingTree, PolicyGenius, HuffPost, National Real Estate Investor and Urban Land.
Read more from John