
What Happens After I Apply for a Credit Card?

Quick Answer
Credit card issuers run identity, fraud and credit checks after you apply for a new credit card. The highly automated process will often quickly tell you whether you are approved, denied or your application is pending.
Credit card applications are often easy to fill out and submit, and you'll generally get a decision within a few seconds. However, a lot is happening behind the scenes when you apply. Here's an overview of what creditors do, how they might respond and how you can improve your chances of quickly getting approved for a new credit card.
Your Identity Will Be Verified
Credit card issuers don't want to give credit cards to fraudsters and identity thieves, and they can use different types of checks and verifications to detect criminals. For example, they might compare the personal information from a credit application and credit report, or examine your credit history for signs of fraudulent activity.
Best credit cards of 2026
Compare cards from our partners with intro bonuses, cash back or points offers, and annual fees as low as $0.
Offers from our partners
Wells Fargo Reflect® Card
Intro APR:0% intro APR for 21 months from account opening on purchases and qualifying balance transfers
Ongoing APR:17.74%, 24.24%, or 28.49% Variable APR
Annual Fee:$0

Wells Fargo Active Cash® Card
Intro APR:0% intro APR for 12 months from account opening on purchases and qualifying balance transfers
Ongoing APR:18.74%, 24.74%, or 28.74% Variable APR
Annual Fee:$0

Blue Cash Preferred® Card from American Express
Intro APR:0% on Purchases and Balance Transfers for 12 months
Ongoing APR:19.74%-28.74% Variable
Annual Fee:$0 intro annual fee for the first year, then $95.

Credit One Bank® Platinum Rewards Visa® Card
Ongoing APR:29.74% Variable
Annual Fee:$39

Credit One Bank® Platinum X5 Visa Signature® Metal Card
Ongoing APR:29.74% Variable
Annual Fee:$95

Avant® Cashback Rewards Mastercard®
Ongoing APR:35.99%*
Annual Fee:$75*

Bank of America® Customized Cash Rewards credit card
Intro APR:0% Intro APR for 15 billing cycles for purchases, and for any balance transfers made in the first 60 days
Ongoing APR:17.74% - 27.74% Variable
Annual Fee:$0

Bank of America® Unlimited Cash Rewards credit card
Intro APR:0% Intro APR for 15 billing cycles for purchases, and for any balance transfers made in the first 60 days
Ongoing APR:17.74% - 27.74% Variable
Annual Fee:$0
See all our best credit cards for 2026.
Your Credit Will Be Checked
Credit card issuers also need to make sure that cardholders can afford a new credit card payment, which is why you'll be asked about your income and monthly housing expenses. Card issuers use credit scores to determine who qualifies for a credit card, and the interest rate and credit limit on the new account.
Many card issuers will request one of your credit reports and a score based on the report, such as a FICO® ScoreΘ or VantageScore® credit score. However, some credit card issuers will pull two or three of your reports to make a decision. The credit check results in a hard inquiry on each of the credit reports that the issuer requests.
There isn't necessarily a minimum credit score that guarantees you'll get approved for a credit card. Partially, this is because card issuers might use custom scores in addition to a FICO or VantageScore credit score. Additionally, issuers could have specific rules for approving or denying credit card applications regardless of the credit score. For example, you might have an excellent credit score and still get denied if you recently opened multiple credit cards.
You'll Find Out the Status of Your Application
The fraud and credit check process is highly automated, and it often only takes a few seconds to get a result. There are three potential outcomes:
Your Application Is Approved
If your application is approved, you'll find out your card's annual percentage rate (APR) and credit limit.
Some issuers may share a credit card number and details right away, so you can use your account for online purchases. Or, you might be able to add your new card account to a mobile wallet. Otherwise, you'll have to wait for your new card to arrive in the mail to start using it.
The new credit card will also be reported to the credit bureaus (Experian, TransUnion and Equifax). However, it can take around 30 to 60 days for the account to show up in your credit report. Once it does, the account's information, including its age, payment history, credit limit and reported balance, can affect your credit scores.
Your Application Is Denied
When your application is denied, you won't get the credit card but the hard credit inquiry will still stay on your credit report for two years.
The credit card issuer will send you an adverse action letter, which tells you that it denied your application due, at least in part, to information from your credit report. The letter will also tell you the credit score that the issuer used, including the type of score and which credit report it's based on.
You can call the credit card issuer if you want to ask it to reconsider your application. For example, maybe you were denied because your credit reports were frozen. Or, perhaps you have other cards from the issuer, and it didn't want to extend you more credit. You might be able to get a decision reversed if you thaw your reports or ask the issuer to move available credit from an existing card to the new card.
Your Application Needs Further Review
Sometimes, an application gets caught in limbo. You're not denied right away, but you also won't get approved unless you can share additional information with the issuer.
For instance, if you applied for a small business credit card, the issuer might want you to share documents to verify that you own the business. Or, maybe you need to share additional identity or income verification documents.
When your application is pending, you may be able to check the current status via the issuer's website. Or, call the issuer to find out what's going on and see if you can help resolve it. If you don't do anything, your application might wind up getting denied.
How Long Does It Take to Get a Credit Card?
It may take around one to two weeks for your new credit card to arrive in the mail once you're approved. If you need the card sooner, you can try calling the card issuer and asking them to expedite the mailing. However, they aren't required to do this, and may charge a fee for expedited shipping.
The instant use credit cards don't ship faster, but you can use the card account before you receive the physical card. Many American Express cards offer instant card numbers, and this is commonly a feature on store cards—such as when you get a new credit card when checking out at a department store.
How to Improve Your Chances of Getting Approved for a Credit Card
You might not be able to guarantee that you'll get approved for a new credit card, but you can take steps to increase your chances, such as:
- Improve your credit score: Making on-time bill payments and paying down credit card balances can help you increase your credit score over time. Try Experian Boost®ø, which uses your on-time cellphone, streaming and utility bills to give your credit scores a bump, if you're looking for a quick way to try to improve your credit scores.
- Thaw your credit reports: Make sure your credit reports aren't frozen when you apply for new credit. You can request temporary thaws, submit your application and then have your reports automatically frozen again.
- Review what you can include as income: Your income can affect your approval and credit limit, and you may be able to include shared household income and several types of non-wage income on the credit card application.
- Get prequalified: Some credit card issuers offer prequalifications that you can use to check your chances of getting approved for a card without affecting your credit score.
Instantly raise your credit scoresø
Add any bank accounts you use to pay your bills. Your information remains private.
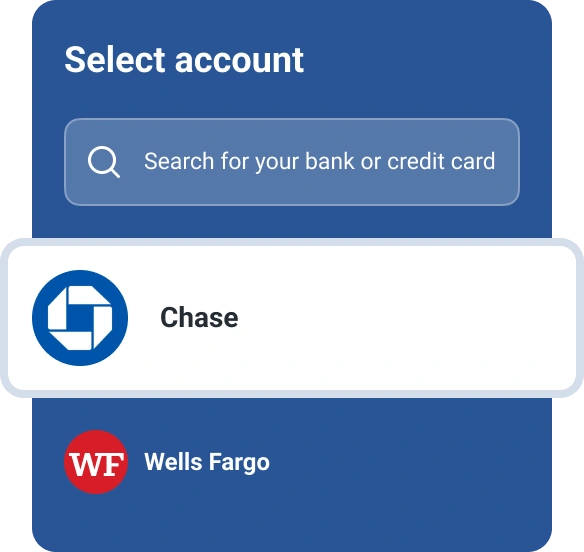
We’ll detect bills with on-time payments, and you can add them to your Experian credit file.
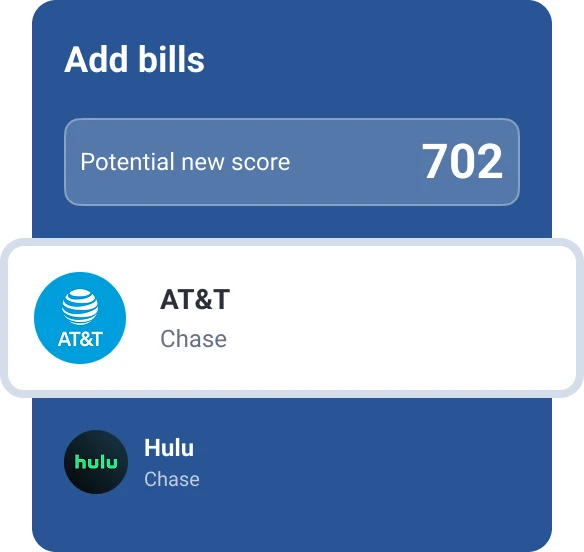
You’ll find out right away if your credit scores increased and by how many points.
Get Matched With a Credit Card
Rather than going from one card issuer to the next, you can use credit card aggregator tools like Experian card comparison tool to get matched with credit card offers based on your credit profile. Using this tool doesn't affect your credit scores, and you can easily compare the offers to figure out which one is best for you before applying.
Don’t apply blindly
Apply for credit cards confidently with personalized offers based on your credit profile. Get started with your FICO® Score for free.
See your offers
About the author

Louis DeNicola
Louis DeNicola is freelance personal finance and credit writer who works with Fortune 500 financial services firms, FinTech startups, and non-profits to teach people about money and credit. His clients include BlueVine, Discover, LendingTree, Money Management International, U.S News and Wirecutter.
Read more from Louis