
 By Ben Luthi
How Does Credit Card Rental Car Insurance Work?
By Ben Luthi
Quick Answer
Many credit cards offer rental car insurance, but the coverage is often secondary to your personal auto policy. It also doesn't protect you from all of the potential costs you may incur in the event of an accident.
When renting a car, you may choose to rely on your credit card's rental car insurance instead of buying the coverage car rental agencies offer. However, it's important to understand what your card's coverage includes—and, more crucially, what it doesn't.
Before you rent a car, here's what to know about how rental car insurance on your credit card works, like how it's typically secondary to your car insurance, along with the potential advantages and disadvantages.
How Does Credit Card Rental Car Insurance Work?
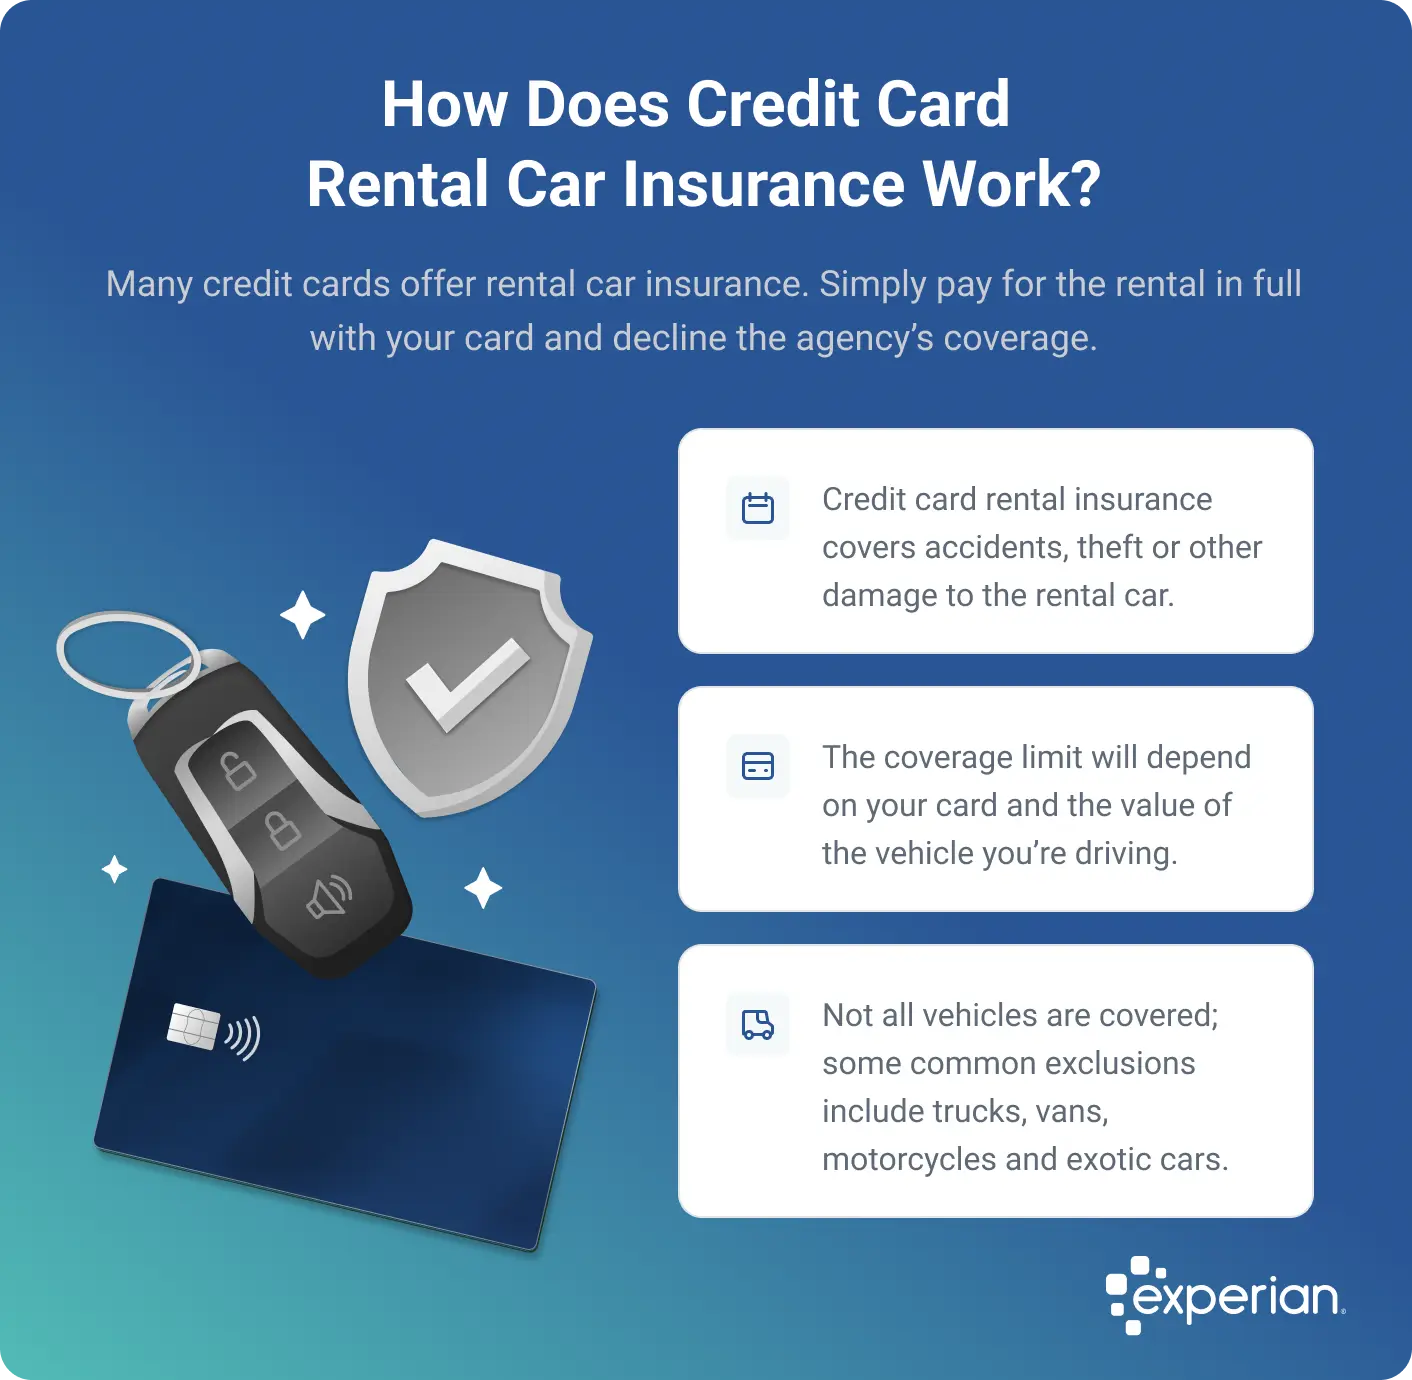
If you have a credit card that offers rental car insurance, you can activate it by paying for your rental car in full with the card and declining the rental agency's coverage.
Tip: Rental car insurance coverage is either collision damage waiver (CDW) or loss damage waiver (LDW) insurance. CDW covers damage in the event of an accident, while LDW also includes theft of the vehicle. It's key to clarify what type of coverage you're getting.
If you get in an accident, the insurance your credit card provides may cover some or all of the costs if your rental car is damaged or stolen. However, this coverage is limited in scope and varies greatly from the coverage you may get from your personal auto insurance policy or even from rental agency insurance.
- Coverage amounts: The coverage limit will depend on your card and the value of the vehicle you're driving, but it usually ranges from $50,000 to $75,000.
- Coverage periods: Depending on your card issuer, you may only be covered for 15 consecutive days traveling in the U.S. and 31 consecutive days when traveling abroad.
- Vehicle types: Not all vehicles are covered by your card's policy. Some common exclusions include trucks, large vans, motorcycles and expensive or exotic cars.
What Does Credit Card Rental Car Insurance Cover?
Specific terms vary by card, but here's what you can generally expect credit card rental insurance to cover:
- Damage to your rental vehicle sustained in a collision
- Theft of the rental vehicle
- Vandalism
- Fire and weather damage
- Loss-of-use charges, or the loss of income for the rental agency while the vehicle is being repaired or replaced
What Does Credit Card Rental Car Insurance Not Cover?
The list of what your credit card doesn't cover is typically longer than the list of what it does. Again, terms can vary by card. But, in general, you typically won't get coverage for the following:
- Personal injuries and property damage you cause in an accident
- Lawsuits arising from damage or injury to others
- Medical expenses for you and others in your vehicle
- Loss or theft of your personal belongings
- Wear and tear
- Mechanical breakdowns
- Damage caused during off-road operation of the vehicle
Credit card issuers may also have limitations related to certain parts and damage or based on the circumstances of the accident. For example, you likely won't have coverage if the vehicle was damaged or stolen due to intentional acts, lack of reasonable care, the influence of alcohol or drugs or illegal activities.
Learn more: What Does Car Insurance Cover?
Primary vs. Secondary Coverage
Credit card rental car insurance is typically secondary in nature, which means you'll be required to file a claim with your personal auto policy before the coverage you receive through your credit card kicks in. Your credit card benefit will cover anything your personal policy won't.
For example, if you get in an accident and the damages total $40,000, you'd need to first file a claim with your personal auto insurance policy. The insurer agrees to cover the $40,000 minus your $1,000 deductible.
After paying the deductible out of pocket, you can file a second claim with your credit card's insurance provider to get a reimbursement for the $1,000 deductible.
If you're traveling in another country, you don't have a personal auto insurance policy or your card offers primary coverage, your card's coverage will be your primary protection, and you don't need to involve your personal auto insurer.
Learn more: What Is Secondary Car Insurance Coverage?
Which Credit Cards Offer Rental Car Insurance?
Many credit cards offer rental car insurance in some form or another. While it's most common among travel and premium credit cards, you may also get it with cash back credit cards and even some non-rewards credit cards.
That said, rental car insurance is just one of many benefits a credit card can provide. As you shop around and compare your options, it's important to look at the total value a card offers to determine if it's right for you.
Best rewards cards of 2026
Compare cards from our partners that earn points, cash back or miles on everyday spending.
Offers from our partners
American Express Platinum Card®
Intro bonus:
As High As 175,000 points. Find Out Your Offer.
You may be eligible for as high as 175,000 Membership Rewards® Points after spending $12,000 in eligible purchases on your new Card in your first 6 months of Membership. Welcome offers vary and you may not be eligible for an offer.
Ongoing APR:See Pay Over Time APR
Rewards:
1x - 5x (Points per dollar)
Get more for your travels with 5X Membership Rewards® points on all flights and prepaid hotel bookings through American Express Travel®, including Fine Hotels + Resorts® and The Hotel Collection bookings. You earn 5X points on flights purchased directly from airlines or through American Express Travel® on up to $500,000 on these purchases per calendar year.
Annual Fee:$895
Costco Anywhere Visa® Card by Citi
Ongoing APR:18.99% - 26.99% (Variable)
Rewards:
1% - 5% (cash back)
Earn 5% cash back rewards on gas at Costco and earn 4% cash back on other eligible gas and electric vehicle (EV) charging purchases for the first $7,000 combined spend per year, and then 1% thereafter. 3% cash back on restaurants and eligible travel purchases and eligible travel, including Costco Travel. 2% cash back on all other purchases from Costco and Costco.com. 1% cash back on all other purchases.
Annual Fee:$0
First Latitude Secured Mastercard® Cash Back Rewards
Ongoing APR:27.74% Variable
Rewards:
1% - 10% (cash back)
Earn up to 10% Cash Back on purchases at participating merchants that fit your lifestyle—from dining and grocery to retail and more—plus 1% Cash Back on payments made to your First Latitude Card.^^
Annual Fee:$0
Citi® / AAdvantage® Globe™ Mastercard®
Ongoing APR:19.74% - 29.74% (Variable)
Rewards:
1x - 6x (Miles per dollar)
Earn 6 AAdvantage® miles for every $1 spent on eligible hotels booked through aadvantagehotels.com. Earn 3 AAdvantage® miles for every $1 spent on eligible American Airlines purchases. Earn 2 AAdvantage® miles for every $1 spent at restaurants, including takeout and delivery. Earn 1 AAdvantage® miles for every $1 spent on all other purchases.
Annual Fee:$350
Credit One Bank® Wander® American Express® Metal Card
Ongoing APR:29.74% Variable
Rewards:
1% - 10% (cash back)
Earn 5% cash back rewards on eligible dining, gas, & travel purchases, 1% cash back rewards on all other purchases, and 10% cash back rewards on eligible hotel and car rentals booked using the Credit One Bank travel partner. Cash back rewards will be awarded as rewards points redeemable for a statement credit, gift cards, travel, and more. Terms apply.
Annual Fee:$95
Delta SkyMiles® Gold American Express Card
Intro bonus:
As High As 80K Miles + $250 Statement Credit
You may be eligible for as high as 80,000 Bonus Miles and a $250 Statement Credit after you spend $3,000 in eligible purchases on your new Card in your first 6 months of Card Membership. Apply to find out your offer. Terms Apply. Offer ends 11/04/2026.
Ongoing APR:19.74%-28.74% Variable
Rewards:
1x - 2x (Miles per dollar)
When you use your Delta SkyMiles® Gold American Express Card, you can earn: 2X miles on Delta Purchases, 2X miles at restaurants, 2X miles at U.S. supermarkets, 1X miles on all other eligible purchases. Every mile you earn brings you closer to the places you want to go. Turn them into your next trip, use them for seat upgrades, and more.
Annual Fee:$0 introductory annual fee for the first year, then $150.
Delta SkyMiles® Platinum American Express Card
Intro bonus:
As High As 90K Miles + $300 Statement Credit
You may be eligible for as high as 90,000 Bonus Miles and a $300 Statement Credit after you spend $4,000 in eligible purchases on your new Card in your first 6 months of Card Membership. Apply to find out your offer. Terms Apply. Offer ends 11/04/2026.
Ongoing APR:19.74%-28.74% Variable
Rewards:
1x - 3x (Miles per dollar)
Earn 3X Miles on Delta purchases and purchases made directly with hotels. Earn 2X Miles at restaurants worldwide including takeout and delivery in the U.S., and at U.S. supermarkets. Earn 1X Miles on all other eligible purchases.
Annual Fee:$350
Hilton Honors American Express Surpass® Card
Intro bonus:
130,000 Points
Earn 130,000 Bonus Points plus a Free Night Reward after you spend $3,000 in purchases on the Hilton Honors American Express Surpass® Card in the first 6 months of Card Membership. Offer ends 01/13/2027.
Ongoing APR:19.74%-28.74% Variable
Rewards:
3x - 12x (Points per dollar)
Earn 12X Hilton Honors Bonus Points for each dollar of eligible purchases charged on your Card directly with a hotel or resort within the Hilton portfolio. Earn 6X Hilton Honors Bonus Points for each dollar of eligible purchases on your Card at U.S. restaurants, at U.S. supermarkets, and at U.S. gas stations. Earn 4X Hilton Honors Bonus Points for each dollar of U.S. Online Retail purchases. Earn 3X Hilton Honors Bonus Points for all other eligible purchases on your Card.
Annual Fee:$150
See all our best rewards credit cards for 2026.
How to File a Claim Through Your Credit Card's Rental Car Insurance
Remember that if your card offers secondary coverage, you'll need to first file a claim with your primary auto insurance company. However, if you have primary coverage or your personal policy doesn't cover the full extent of the damage, the claims process can vary by card issuer.
That said, here are some general guidelines for filing a claim with your card issuer's insurance provider:
- Contact the benefits administrator. You can get the phone number from your card's benefits guide or by calling the number on the back of your card. The benefits administrator may allow you to file a claim online or require you to fill out a form.
- Provide documentation. When filing your claim, you'll typically need to provide certain documents, such as an accident report, a police report, a copy of the rental agreement, a repair estimate and photos of the damage. You may also need to provide a copy of your credit card statement showing you paid the full rental fee with your card.
- Wait for the payout. Once you've submitted all of the required documentation, you'll typically receive a payout of the claim within 15 to 30 days.
It's important to note that you may have anywhere from 30 to 100 days to file a claim to qualify for coverage—or as soon as reasonably possible. The benefits administrator will also typically set a deadline for providing documentation. Before you reach out, it's important that you understand the requirements to avoid being forced to foot the bill.
Learn more: Steps to Take After a Car Accident
Choose the Right Credit Card for You
While credit card rental car insurance can provide some value, there are many other valuable benefits that credit cards can offer, including rewards, 0% intro APR promotions, travel perks and more. If you're looking for a new credit card, Experian's card comparison tool can match you with offers based on your credit profile so you can compare your options side by side and choose the best fit for you.
Don’t apply blindly
Apply for credit cards confidently with personalized offers based on your credit profile. Get started with your FICO® Score for free.
See your offers
About the author
Ben Luthi
Ben Luthi has worked in financial planning, banking and auto finance, and writes about all aspects of money. His work has appeared in Time, Success, USA Today, Credit Karma, NerdWallet, Wirecutter and more.
Read more from Ben